What Happens to Your Business If You Can’t Show Up Tomorrow?
What Happens to Your Business If You Can’t Show Up Tomorrow? Most business owners spend the majority of their time thinking about growth. They focus on increasing revenue, finding new customers, hiring employees, improving operations, and building something that will provide financial freedom for themselves and their families. It’s the mindset that every successful entrepreneur develops. After all, businesses don’t grow by accident…they grow through vision, hard work, and consistent execution.
What many business owners don’t spend enough time considering, however, is what happens if they suddenly become unable to run the business they’ve worked so hard to build.
Not because they decided to retire. Not because they sold the company. But because life unexpectedly interrupted the plan.
As a financial coach, I’ve found that one of the greatest financial risks facing entrepreneurs isn’t competition, inflation, or even an economic downturn. It’s the possibility that the owner—the person who drives sales, makes decisions, manages employees, and maintains customer relationships…can no longer show up.
For most small and medium-sized businesses, the owner is far more than an employee. They are the engine that keeps everything moving. When that engine suddenly stops, even temporarily, the financial impact can begin almost immediately.
One of the first concepts I teach every client is that businesses don’t survive on optimism; they survive on cash flow. Revenue is important. Profit is important. Growth is important. But cash flow is what pays employees on Friday, keeps vendors satisfied, covers loan payments, and allows a business to continue operating during difficult periods. When cash flow is interrupted, even a profitable company can begin experiencing serious financial stress.
Imagine a business owner who employs twenty people. The company has been successful for years. Customers are loyal, the team is experienced, and the future looks bright. Then, without warning, the owner suffers a serious heart attack, is diagnosed with cancer, or is involved in an automobile accident that requires months of recovery. The owner survives, but suddenly cannot work.
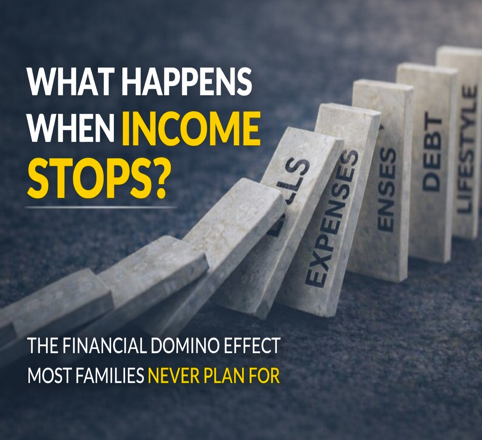
During the first week, everyone assumes things will return to normal. Employees step up, customers are understanding, and optimism remains high. But as the weeks turn into months, reality begins setting in. Sales start slowing because no one develops relationships quite like the owner. Important decisions get delayed. Customers begin looking elsewhere. Employees start wondering about the company’s future. Meanwhile, payroll still has to be met every two weeks. Rent is still due. Equipment leases continue. Taxes don’t stop simply because someone is in the hospital. Vendors still expect payment, and lenders still expect their monthly checks.
The financial pressure builds quietly at first, but eventually it accelerates. Conversations that once focused on expansion begin shifting toward survival. Instead of discussing new opportunities, the owner and their family begin asking how much longer they can continue operating.
Ironically, one of the biggest misconceptions I encounter is that life insurance is only valuable after someone dies. While the death benefit is certainly important, many modern permanent life insurance policies include living benefits that may allow policyholders to access a portion of their death benefit while they are still living if they experience certain qualifying medical conditions. From a financial planning perspective, that changes the conversation dramatically.
Rather than viewing life insurance as something designed only to protect surviving family members, I encourage business owners to think of it as part of their overall liquidity strategy. During a major health event, access to capital can make the difference between preserving a business and watching years of work slowly disappear. Having available funds may help continue payroll, pay business expenses, hire temporary management, preserve customer relationships, or simply provide enough breathing room to focus on recovery instead of worrying about whether the business can survive another month.
Liquidity creates options, and options create time.
That may sound like a simple statement, but it is one of the most important financial principles I know. When unexpected events occur, time becomes incredibly valuable. Time allows families to make thoughtful decisions instead of emotional ones. Time allows businesses to retain employees instead of laying them off. Time allows owners to recover without feeling forced to sell assets, liquidate retirement accounts, or close a business they spent decades building.
I’ve seen business owners spend twenty or thirty years creating tremendous value, only to watch much of it disappear because they lacked accessible capital during a medical crisis. Their business wasn’t failing because it wasn’t profitable. It was failing because it ran out of liquidity before the owner was able to return.
This is why I believe every business owner should ask themselves a few difficult questions. If you couldn’t work tomorrow, how long could your business continue operating without you? Would payroll still be covered? Would your spouse know what to do? Could someone temporarily manage the company? Would customers remain loyal? Most importantly, would your business have enough financial resources to survive six months—or even a year—without your direct involvement?
These aren’t comfortable questions, but they are necessary ones. Preparing for life’s uncertainties isn’t pessimistic. It’s responsible leadership. Every entrepreneur understands business risk. Yet many overlook one of the largest risks they personally represent to the company they own.
It’s also important to recognize that insurance alone is not the entire solution. A strong financial strategy includes emergency reserves, appropriate disability planning, succession planning, estate planning, tax-efficient wealth strategies, and business continuity planning. Permanent life insurance with living benefits, when properly designed and appropriately funded, can become one valuable component within that larger financial framework. The objective isn’t simply to own another policy; it’s to create financial resilience.
Business owners routinely insure their buildings, vehicles, equipment, inventory, and even cyber liability. Yet the most valuable asset in many companies isn’t any of those things…it’s the owner. Your experience, leadership, relationships, and ability to generate revenue often represent the greatest value your business possesses. Protecting that asset deserves just as much attention as protecting everything else on the balance sheet.
Building a successful business requires enormous sacrifice. It demands long hours, difficult decisions, personal financial risk, and years of consistent effort. That’s precisely why protecting what you’ve built should never become an afterthought. The goal isn’t to expect tragedy. The goal is to ensure that if life takes an unexpected turn, one difficult season doesn’t erase decades of hard work.
As a financial coach, my role extends far beyond helping clients accumulate wealth. I believe true financial planning is about helping people create resilience. It’s about building a financial foundation strong enough to withstand uncertainty while preserving opportunities for the future. When business owners have access to liquidity, they have choices. When they have choices, they have time. And when they have time, they dramatically increase the likelihood that both their family and their business will emerge from life’s unexpected challenges stronger than before.
If you’re a business owner, don’t wait until a crisis forces these conversations. Ask the questions now, while you still have the luxury of planning instead of reacting. The best financial strategies are rarely created during an emergency…they’re built long before one ever occurs.
This article is for general educational purposes only and is not tax, legal, accounting, or investment advice. Strategies depend on individual circumstances and current law. Please review any strategy with your CPA, tax attorney, or other qualified professional before acting. Insurance products are subject to underwriting and carrier terms.